Brazilian nickel deal tests Europe’s minerals strategy
Subscribe to our free newsletter today to keep up to date with the latest mining and minerals news.
Europe’s review of MMG’s proposed purchase of Anglo American’s Brazilian nickel business is becoming a test of how governments define mineral security.
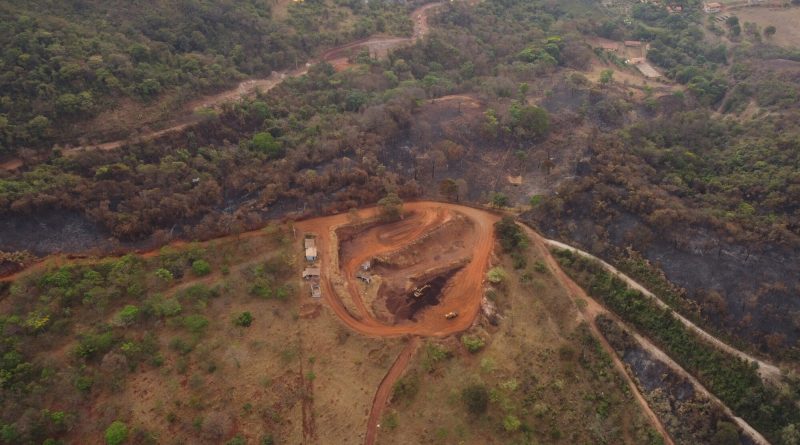
The transaction, valued at up to $500 million, would give MMG control of Anglo American’s Barro Alto and Codemin ferronickel operations in Brazil, along with the Jacaré and Morro Sem Boné development projects.
The two operating sites produce about 40,000 metric tons of nickel in ferronickel each year. That output matters because ferronickel is used mainly by stainless steel producers, including manufacturers in Europe.
For Anglo American, the sale is part of a wider portfolio shift toward copper, premium iron ore and crop nutrients. For MMG, which is controlled by China’s state-owned Minmetals group, the acquisition would mark its entry into Brazilian mining and primary nickel production.
The wider importance of the deal goes beyond corporate strategy.
Producing mines are increasingly being judged not only by their reserves, operating costs and value, but also by who owns them and where their output may be sold.
That change could affect mining investment far beyond Brazil.
Producing mines are becoming strategic assets
Mineral security debates often focus on exploration and undeveloped resources. Existing production can matter more in the near term.
Operating mines already have infrastructure, employees, processing capacity and established routes to market. In many cases, they also have permits that took years to secure.
That makes existing production difficult to replace.
This matters for nickel because the market has changed quickly. Indonesia has become the main source of new nickel supply, while China has built a strong position across several stages of mineral processing.
Brazil offers another source of production. It has a large mining industry, established infrastructure and substantial undeveloped mineral resources.
The Anglo American assets therefore offer more than current output. Jacaré and Morro Sem Boné also give the buyer options for future development.
For MMG, the combination offers existing production alongside projects that could extend or increase output over time.
For Europe, the concern is whether control of those assets could eventually affect the availability of ferronickel to European stainless steel producers.
The European Commission has raised concerns that output could be redirected away from European customers after the acquisition. That could reduce supply options and raise costs for steelmakers.
This is where competition policy begins to overlap with industrial policy.
MMG is not combining the assets with a large existing Brazilian ferronickel business. It is entering the market. Under a conventional competition assessment, that distinction matters.
Policymakers are now asking a broader question. Could ownership of a producing mineral asset create a future supply risk even when the buyer does not already dominate that market?
That is a wider test than competition policy has traditionally applied.
Europe’s mineral ambitions depend on more than ownership
The problem for Europe is that restricting ownership does not create additional supply.
If policymakers want a more diverse minerals market, more mines and processing plants will need financing outside the countries that currently dominate production.
That can be expensive.
The International Energy Agency has warned that mineral processing remains concentrated even as new mining projects appear across a wider range of countries. In some supply chains, new refining capacity outside the leading producer can carry much higher capital and operating costs.
Diversification is therefore difficult to achieve through regulation alone.
Mining companies base investment decisions on expected returns. If new mines face higher construction costs, longer permitting periods or weaker infrastructure, they may need stronger prices or firmer customer commitments to justify investment.
This creates a gap between mineral policy and mining economics.
Governments may want supply chains spread across more countries. Companies still need projects that can compete commercially.
That tension becomes more visible when large miners sell assets they no longer consider central to their portfolios.
Anglo American’s decision to leave nickel is a capital allocation choice. Another company still needs to buy, operate and invest in those mines.
If regulators restrict the pool of potential buyers, they may also affect asset values and future investment decisions.
The wider question is therefore not only who should be allowed to buy a mine. It is also who is willing to finance that mine through the next commodity cycle.
Geopolitics is changing how mineral deals are judged
China’s role makes that question harder.
MMG is controlled by China Minmetals, a state-owned company. European governments are also trying to reduce their exposure to concentrated supply chains after years in which China increased its position across mineral refining and processing.
Export restrictions have added to those concerns.
Mineral ownership is therefore becoming part of a wider debate about industrial resilience. Governments are paying closer attention to whether strategic materials will remain available during periods of political or trade tension.
Nickel is an interesting case because it does not fit neatly into the usual discussion around critical minerals.
Much recent attention has focused on nickel used in electric vehicle batteries. Ferronickel, however, is primarily an industrial input for stainless steel.
That makes the Anglo American assets relevant to established European manufacturing sectors, not only newer clean technology supply chains.
It also shows how the definition of a strategic mineral can expand when supply becomes more concentrated.
Europe’s challenge will be separating credible supply risks from assumptions based mainly on ownership.
Blocking acquisitions or placing conditions on them may preserve access in some cases. But those measures do little to address the wider problem if alternative mines, smelters and processing projects are not being built.
Mineral policy may therefore depend increasingly on finance as well as regulation.
Long-term purchasing agreements, project funding, faster permitting and investment in processing capacity could all become more important if Europe wants reliable supply from a wider group of producers.
For miners, that could change how transactions are assessed.
The highest bidder may no longer be enough. Governments may increasingly examine a buyer’s ownership, downstream interests and plans for production before approving the transfer of strategically important assets.
That would make mineral security a direct factor in mining mergers and acquisitions.
The Brazilian nickel deal is an early example of that shift.
Its importance lies not only in the ferronickel produced today, but in a broader question for the industry: If governments want more secure mineral supply, they may also need to decide who will finance, own and operate the mines that provide it.
Source