Critical minerals processing gets $500M US boost
Subscribe to our free newsletter today to keep up to date with the latest mining and minerals news.
The US Department of Energy’s decision to allocate $500 million toward domestic critical materials processing reflects a clear shift in industrial policy. The funding targets a segment of the supply chain that has remained concentrated overseas, particularly in China, where much of the world’s refining capacity is located.
Critical minerals such as lithium, cobalt, nickel and rare earth elements support electric vehicle batteries, renewable energy infrastructure and defense technologies. Despite their importance, the US has relied on imports for both raw materials and processing. That reliance has exposed weaknesses in supply security.
The funding initiative aligns with broader efforts to reshore industrial capabilities and strengthen energy and manufacturing systems. Policymakers are focusing on midstream processing, where much of the value creation and strategic control exists.
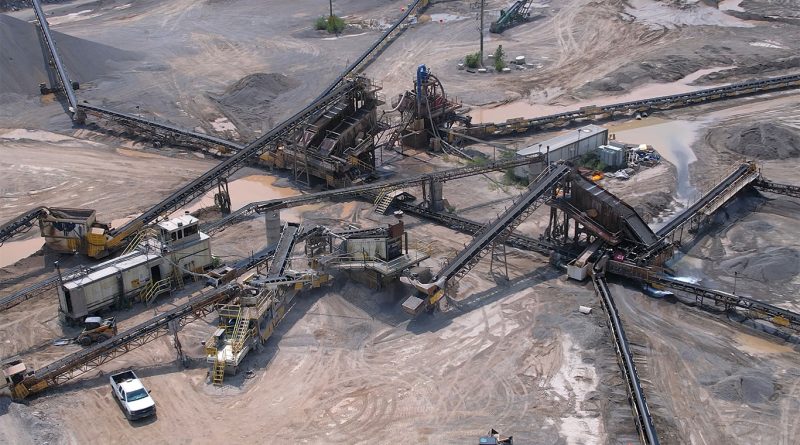
This approach reflects a more precise understanding of supply chains. Mining alone does not deliver independence. Processing capacity determines whether raw materials can be converted into inputs for advanced manufacturing. Without it, domestic extraction has limited strategic impact.
Supply chain vulnerabilities meet rising demand
The timing of the funding reflects both supply fragility and accelerating demand. Global demand for critical minerals is expected to rise sharply over the next decade as electrification expands. Electric vehicles are driving increased demand for lithium and nickel, while rare earth elements remain necessary for wind turbines and electronics.
Supply chains remain highly concentrated. China’s share of global processing capacity, in some cases between 60 percent and 90 percent, creates structural imbalance. This concentration introduces exposure to export restrictions, pricing pressure and geopolitical tension.
The US and its allies are responding to these risks. Recent supply chain disruptions have demonstrated how quickly constraints can affect manufacturing output. In energy markets, these disruptions could slow deployment and increase costs.
The International Energy Agency projects that demand for critical minerals could grow several times over by 2040. Meeting that demand requires both increased mining and expanded processing infrastructure. Without investment in refining, supply chains will remain constrained.
The economics and complexity of building processing capacity
Developing domestic processing capacity presents financial and operational challenges. Refining facilities require significant capital investment, often reaching hundreds of millions of dollars. Regulatory requirements can extend timelines and increase uncertainty.
Permitting remains a major constraint. Environmental standards add complexity to project development, while competing regions may offer faster approval processes. This affects the competitiveness of domestic projects.
Technical capability also plays a role. Processing critical minerals requires specialized expertise that is not widely available across the current workforce. Addressing this gap will be necessary for scaling operations.
The $500 million funding package is structured to reduce early-stage risk and support project development. By improving project economics, the government aims to attract private investment. Public and private collaboration will be central to advancing these projects.
Progress will take time. Building a processing ecosystem requires coordination across multiple stages, including mining, logistics, refining and manufacturing.
Industrial policy, incentives and market response
The funding initiative is part of a broader industrial policy framework that includes the Inflation Reduction Act and the Bipartisan Infrastructure Law. These policies introduce incentives that support domestic supply chain development.
Tax credits, grants and financing mechanisms are reshaping investment decisions. Projects that were previously uneconomic are now gaining attention from industry participants.
Companies are beginning to respond through partnerships and integration strategies. Linking mining operations with processing and manufacturing offers a way to capture value and reduce exposure to external supply risk.
The focus on processing reflects a shift in policy design. Securing raw materials is not sufficient if intermediate stages remain dependent on foreign capacity. Strengthening midstream capabilities creates a more stable system.
What this means for global competition and supply chains
The US investment in critical minerals processing is likely to influence global supply chains. As domestic capacity grows, trade patterns may shift. Countries that currently dominate processing could face increased competition, particularly if similar policies emerge elsewhere.
New partnerships may also develop. Resource-rich countries and processing hubs are likely to deepen cooperation, with supply security as a central objective.
For companies, the changing environment presents both opportunity and risk. Adjusting to new policy frameworks, cost structures and competitive dynamics will be necessary. Early investment may provide an advantage as supply chains evolve.
The $500 million initiative represents an early stage in a longer process. Expanding domestic processing capacity will require continued funding, coordination and industry participation. Control over processing is becoming a defining element of industrial strategy.
Sources: